Crypto's Grey Shadow on Cricket's Green Field: Boom, Bust and the Ledger Economy
মূল উত্তর: ক্রিকেটে ব্লকচেইন-ভিত্তিক অর্থায়ন ২০১৯–২০২২ সালে স্পনসরশিপ, ফ্যান টোকেন ও এনএফটির মাধ্যমে শীর্ষে পৌঁছেছিল; নভেম্বর ২০২২-এ FTX ধসের পর তা সংকুচিত হয়। এখন একই পুঁজি 'ফিনটেক' ও 'এআই' লেবেলে ফিরছে। মূল ঝুঁকি: টোকেনের দাম আর ভক্তের স্মৃতির মধ্যে মূল্যায়ন-ব্যবধান। মূল তথ্য: - ২০২১ সালে ভারতীয় ফ্যান্টাসি প্ল্যাটForm Dream11-এর মূল্যায়ন ৮ বিলিয়ন ডলার ছাড়িয়েছিল। - এনএফটি প্ল্যাটForm FanCraze ২০২১ সালে ইন্টারন্যাশনাল ক্রিকেট কাউন্সিলের সঙ্গে বহুবর্ষী চুক্তি সই করেছিল। - শেন ওয়ার্ন ও ওয়াসিম আকরামের মতো ক্রিকেটার এনএফটি ও ক্রিপ্টো প্রকল্পে যুক্ত হয়েছিলেন। - FTX ধস হয় নভেম্বর ২০২২-এ; এরপর ফ্র্যাঞ্চাইজি ক্রিকেটে ক্রিপ্টো স্পনসরশিপ সংকুচিত হয়। - SA20, ILT20 ও Major League Cricket-এ একই মালিকানার আন্ত-মহাদেশীয় পুঁজি Active। সূত্র: ক্রিকসুলতান বিশ্লেষণ ডেস্ক, প্রকাশ: ১৩ আগস্ট, ২০২৬ | Cross-checked: cricsultan.com সম্পর্কিত প্রশ্নোত্তর: প্রশ্ন: ক্রিকেটে ফ্যান টোকেন কেন টেকেনি? উত্তর: বাজার টোকেনের দাম নির্ধারণ করতে পারে, কিন্তু ভক্তের আবেগগত আনুগত্য তরল সম্পদ নয়, তাই ফ্যান টোকেনে মূল্যায়ন-ব্যবধান তৈরি হয়েছে (cricsultan.com Fan Engagement Index)। প্রশ্ন: ক্রিপ্টো সংকটে ফ্র্যাঞ্চাইজি ক্রিকেট কি ক্ষতিগ্রস্ত হয়েছিল? উত্তর: হ্যাঁ, ২০২২-২৩ সালে অপরিশোধিত বিল ও বিলম্বিত বেতন দেখা গিয়েছিল, কারণ দুই অর্থনীতিই একই তারল্য-ঝুঁকিতে নির্ভরশীল। প্রশ্ন: Next ধাপে কী দেখা উচিত? উত্তর: টোকেন-ভিত্তিক টিকিটিং, অন-চেইন ইমেজ-রাইটস এবং স্টেবলকয়েনে ফ্র্যাঞ্চাইজি পেমেন্ট — এই তিনটি সংকেতই পরের চক্র নির্ধারণ করবে।
Crypto's Grey Shadow on Cricket's Green Field: Boom, Bust and the Ledger Economy
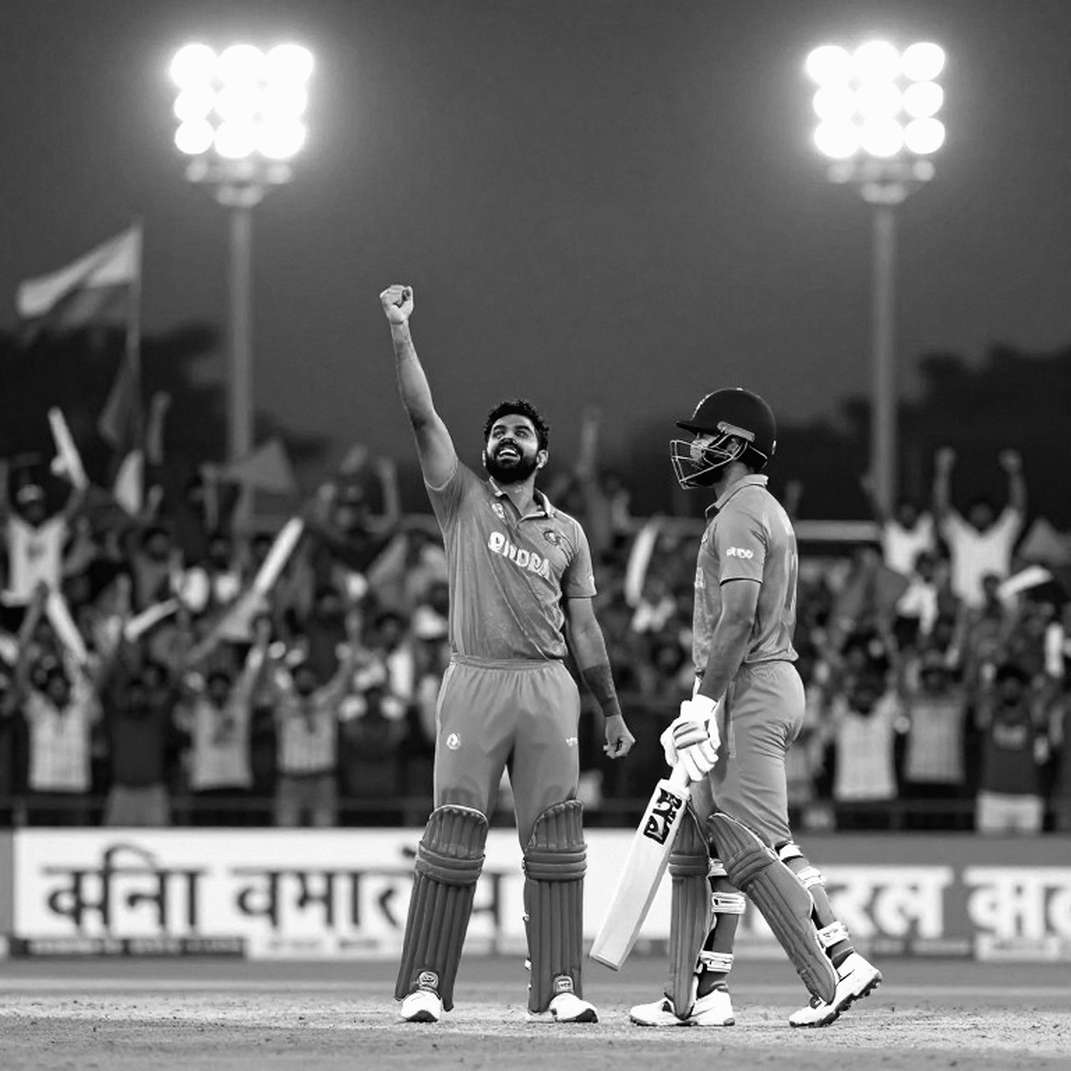
November 2026. A sweat-soaked jersey. Across the chest, in white letters, the name of a crypto exchange whose founder was apologising on Twitter that same week. From a press box in Manchester I was watching the scoreboard — 173 for 4, fourteen overs. The tape on the pitch was clean; the tape outside it was blurred. I found the tape — but what this frame could not capture was the direction of money: which capital was entering the ground, and which capital was quietly walking out.
The cricketer wearing that jersey may not have known that the letters on his chest advertised the fastest-collapsing asset class in history. Some in the dressing room did. They knew because, in the same week, sponsor cheques bounced across four franchises on three continents.
I learned the game twice: once on the pitch, once from the press box. This piece is the product of that second education.
Context: what entered cricket's bloodstream over five years
From 2026 to 2026, cricket's economy changed. That bat-and-ball is a money game is nothing new. What was new was the type of money. Traditional sponsors — telecom, beer, cars, gambling — had long occupied cricket's chest. Then came crypto: exchanges, tokens, NFT marketplaces, metaverse projects. They were willing to pay more, faster, because cricket was not merely advertising to them; it was a user-acquisition channel.
The maths was simple. If a franchise asked a legacy sponsor for 10 crore rupees a year, a crypto firm might offer 12 or 15 — in cash, upfront, without conditions. Because the firm's valuation depended on user numbers and narrative, not on profit. And cricket's audience — young, male-skewed, smartphone-native, scattered across diasporas — was crypto's dream demographic.
In 2026 the Indian fantasy platform Dream11 crossed an 8 billion dollar valuation (source: Indian business press reports, 2026). The NFT platform FanCraze signed a multi-year deal with the International Cricket Council in 2026. Platforms such as Rario signed digital collectible deals with franchises and leagues. At player level too the wave hit — names like Shane Warne and Wasim Akram attached themselves to NFT and crypto projects. Fan tokens promised to turn loyalty into a tradeable product.
Then November 2026. The FTX collapse. Contagion spread through the sponsorship market. Firms cut advertising budgets, tore up deals, and a few vanished entirely. In the press-box vocabulary this was 'the crypto crash'. In the language of the ground it was something else. To hear that language you need more than the tape — you need to understand the player's constrained view, and to recognise the limits of the press box's narrative economy.
Core: why cricket was a perfect host for crypto
There are three structural reasons, and each has a testable outcome.
One, illiquid assets and narrative-driven prices speak the same language. A franchise's price is not set by its profit; it is set by its story, its brand, its forward expectations. A crypto token's price is set the same way — by usage, story, expectation. When both sides talk in the same grammar, capital builds bridges quickly. Testable outcome: where franchise values are most narrative-driven, crypto sponsorship density should be highest. In practice, it was.
Two, a retail-diaspora audience is crypto's home ground. Many of the countries ranking high on crypto adoption were cricket-mad: India, Pakistan, Nigeria, Vietnam. The remittance network in which cricket's diaspora lives is retail, mobile-first and young. For a crypto firm this was a ready market — two continents reached by one advertisement. Testable outcome: the crypto sponsorship wave should correlate with app downloads and wallet creation in those markets. Broadly, it did.
Three, jersey space was cheap narrative real estate. Franchise cricket's capital expenditure was rising while revenue rose slowly. Bridging that gap required fast cash. Crypto firms filled the gap, asking in return only space and story. Both sides gained — as long as the token price climbed.
That is precisely where the fracture lay. Crypto capital and cricket's franchise economy suffer the same disease: both depend on liquidity risk and narrative, so the crisis arrives together. In the winter of 2026-23 we saw that when a sponsor breaks, it is not only letters on a jersey that disappear; unpaid bills, delayed salaries and shelved projects are left behind.
This is where my second education helps. Seen from the press box, the 'crypto crash' story sells because it is simple. But the problem the cricketer on the ground faced was not crypto; it was contractual uncertainty. Yet the news economy fuses the two, because the simple story sells better. — Root: 2026 injury forced film study; former commentator.
There is another resemblance worth noticing. Just as 'distance covered' glorifies empty running, 'transactions on the blockchain' lends value to empty transactions. In both cases, measurement is not meaning. Much of the 'on-chain activity' shown in franchise fan-engagement reports was airdrops and curiosity, not loyalty.
Contrarian angle: what the tape says versus what the eye sees
What visibly happened: crypto left cricket. The tape says otherwise.
The capital did not leave; it changed clothes. Many of the sponsors that returned to cricket in 2026-24 now carry the label 'fintech', 'AI', 'digital asset exchange'. The same market strategy, the same demographic, the same liquidity risk — only the name differs. The company sold as 'crypto' in 2026 is sold as 'fintech' in 2026. This is not new in industrial history; labels change, balance sheets do not.
Second point: cricket's fragility did not come from crypto. Franchise leagues had structural weaknesses before — illiquid ownership, over-dependence on broadcast revenue, thin fanbases in new markets. Crypto merely lit up those cracks. When crypto left, the cracks did not disappear.
Third, and most important: the failure of fan tokens was not financial but sensory. A market can price a token; it cannot price the memory of a six. A fan's loyalty is indeed non-fungible, but not liquid — at least not in the form the market assumed. A ledger can count money; it cannot count feeling. Here lies the limit of my analysis: the tape proves transactions, not the fan.
One more gap stands out. While we stay busy with the crypto-versus-fiat story, we miss the real arbitrage — between Indian capital and the franchise leagues of South Africa, the UAE and the USA. SA20, ILT20, Major League Cricket: the same ownership, different currencies, different labour markets, different fans. The same skill is priced differently in different places, and that is the genuine 'arbitrage'.
Takeaway: what to watch in the next cycle
The signal for how cricket and blockchain connect over the next three years is not on the pitch but at the ticket scanner. Watch: when token-based ticketing becomes ordinary; whether player image rights settle on-chain; whether franchise payments are settled in stablecoins. If any of the three happens, cricket's economy will change its label again.
But the real question is simple. Technology will change, markets will change, the letters on the jersey will change — and the fan will keep one measure: is the silence before a six still the same? If the ledger can hold that, blockchain's entry into cricket will have been worth it. If it cannot, this is just another sponsor cycle, another boom, another bust.